How Australian Casino Players Read a KYC Request and Respond Efficiently
A KYC request from an online casino asks for specific documents to verify identity, age, address or payment ownership. The breakdown of which casino documents are requested and why covers the regulatory reasons behind each category, and reading the request itself is where that knowledge becomes practical for Australian players preparing a response.
A well-prepared response to the first request is faster than submitting documents that miss the stated requirement and waiting for a follow-up.
Read the request before gathering documents
A KYC request may arrive as an in-account notification, a support message or an email. The first step is to read it fully before opening any files or taking any photographs.
The request typically names one or more document categories. Common categories include proof of identity, proof of age, proof of address, proof of payment ownership and source of funds. Each category has a defined purpose and a set of accepted document types. Matching the document to the stated category keeps the review moving efficiently.
Some requests list several categories at once. Others arrive in stages, with a first request for identity followed by a later request for address once the identity document is reviewed. Reading the current request scope avoids sending documents that belong to a later stage.
Proof of identity: what to send
A proof of identity request confirms that the account holder is a real person with a verifiable legal name and date of birth. Accepted documents commonly include a current passport, driver licence or government-issued photo identity card.
The document should show the full legal name, date of birth, photo and an expiry date that places it within the validity period. A document within its validity period carries the strongest evidentiary value.
The image or scan should show all four corners of the document without cropping. Reflections from glass or laminate can obscure security features. Taking the photograph in even, indirect light and checking the preview before submitting produces a cleaner result than a rushed capture.
For Australian players, a current Australian passport or a current state-issued driver licence are the most commonly accepted identity documents at online casinos serving the market. A current, official document in the accepted format completes the category most efficiently.
Proof of age: when it differs from identity
Some requests separate proof of age from general identity verification. This can occur when the identity document sent requires an additional age confirmation, or when the operator’s compliance process requires an additional age confirmation step.
A supplementary document showing the date of birth, such as a birth certificate, can satisfy this category alongside the primary identity document. The request should specify if a separate age document is required or if the identity document is expected to cover both.
Proof of address: what to send
A proof of address request confirms that the residential address in the account matches a current, verifiable source. Accepted documents include recent utility bills, bank statements, government letters or local council correspondence.
The document should show the full legal name, residential address, the issuing organisation and a date within the period specified in the request. Many operators specify a recency window of three months. A document older than this window may be valid as a record but falls outside the request scope.
Digital statements are widely accepted when downloaded directly as a PDF from the source. A PDF downloaded directly from the source is accepted more consistently across operators. Downloading the PDF version removes this uncertainty.
Proof of payment ownership: what to send
When a deposit is made by card, e-wallet or bank transfer, the operator may request evidence that the payment method belongs to the account holder. This step confirms the payment was made by the verified person and supports the operator’s anti-money laundering obligations.
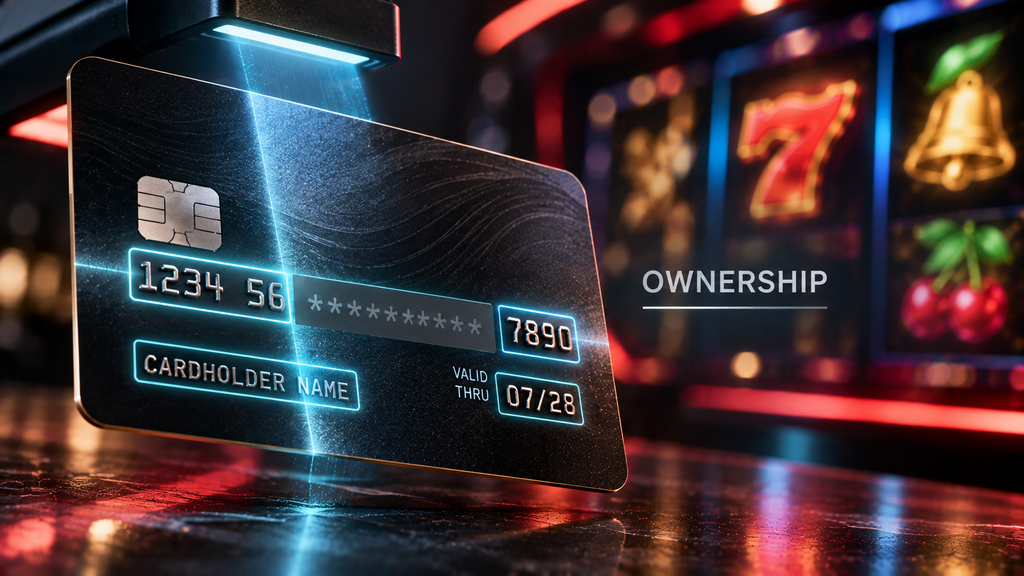
For a card, the request commonly asks for an image showing the name, expiry date and the first six and last four digits. The middle digits and the security code on the back are covered in the image. The operator’s request should state which elements to reveal and which to obscure.
For an e-wallet such as PayPal, Skrill or Neteller, a screenshot of the account showing the registered name and email address satisfies the category at most operators. The account balance is typically covered or cropped from the image.
For a bank transfer, a bank statement showing the account name, BSB and account number, with the balance and unrelated transactions covered, confirms ownership.
Source of funds: when it is requested and what to send
A source of funds request asks the account holder to explain where the deposited money came from. This category is triggered by larger transactions, unusual deposit patterns or a compliance review threshold.
Accepted documents depend on the stated income source. Employment income can be supported by recent payslips or a letter of employment. Business income may require financial statements or a tax return. Asset sales can be supported by a sale contract or settlement statement.
The operator’s request should state which income types are relevant to the account activity being reviewed. Sending documents that address the stated period and amount is more useful than sending a large bundle of unrelated financial records.
For Australian players, a tax return or group certificate from the Australian Taxation Office provides a recognised income confirmation. Superannuation statements, investment account summaries and real estate settlement documents are also commonly accepted where relevant.
Responding through the correct channel
Documents should be submitted through the operator’s official secure upload area within the account, or through a channel the operator has confirmed in writing. Email submission is acceptable when the operator’s support has confirmed the receiving address in the same conversation.
A document sent through an unofficial channel, such as a social media platform or a messaging application, carries higher exposure risk for the account holder. The operator’s confirmed channel is the clearest route for sensitive identity and financial documents.
Following up on a submitted response
After submitting, the account status or verification section should update to reflect the received documents. A status of “under review” or “documents received” confirms the submission was registered.
If the status stays unchanged after 24 hours, a support query with the submission date, document category and a confirmation that the upload completed gives the team a reference to check. The query should avoid resending the documents unless support specifically requests them.
Timing the verification submission
Submitting verification documents before they are requested places the account in a stronger position when a withdrawal triggers a review. Some operators allow proactive document submission through the account settings or a dedicated verification section.
A player who has already submitted identity and address documents before the first withdrawal request reaches the payments step sooner, because the compliance review has fewer outstanding items.
For Australian players expecting to make their first significant withdrawal, checking if the operator accepts early document submission and completing that step during a calm session removes the verification stage from the withdrawal timeline. The documents are on record, and a simple payment review replaces a full identity check.
When a document needs resubmission
A document may need resubmission when the image quality needs improvement, the document sits outside the stated validity period, the category requires a different document type or certain elements need clearer visibility.
The resubmission request should identify the specific element to address. Addressing only the stated issue in the replacement submission is more efficient than resending all documents from the original response.
A clear image under even lighting, with all corners visible and the required elements showing, resolves the most common image-quality returns. A document within the stated validity period resolves the most common date-related returns.
Keeping a record of the verification process
A short log of the verification interaction includes the date of the request, the categories requested, the documents submitted, the submission date and any follow-up messages.
This log supports a focused support query if the verification status changes unexpectedly, and keeps the full record of the process accessible in one place for the duration of the account relationship.
Australian players who read the KYC request category, prepare the correct document type, submit through the confirmed channel and follow up with a specific reference can complete verification efficiently and keep the account in a clear state for deposits and withdrawals.